Productivity, Online Tools, Finance
How Monthly Contributions Change an Emergency Fund Timeline
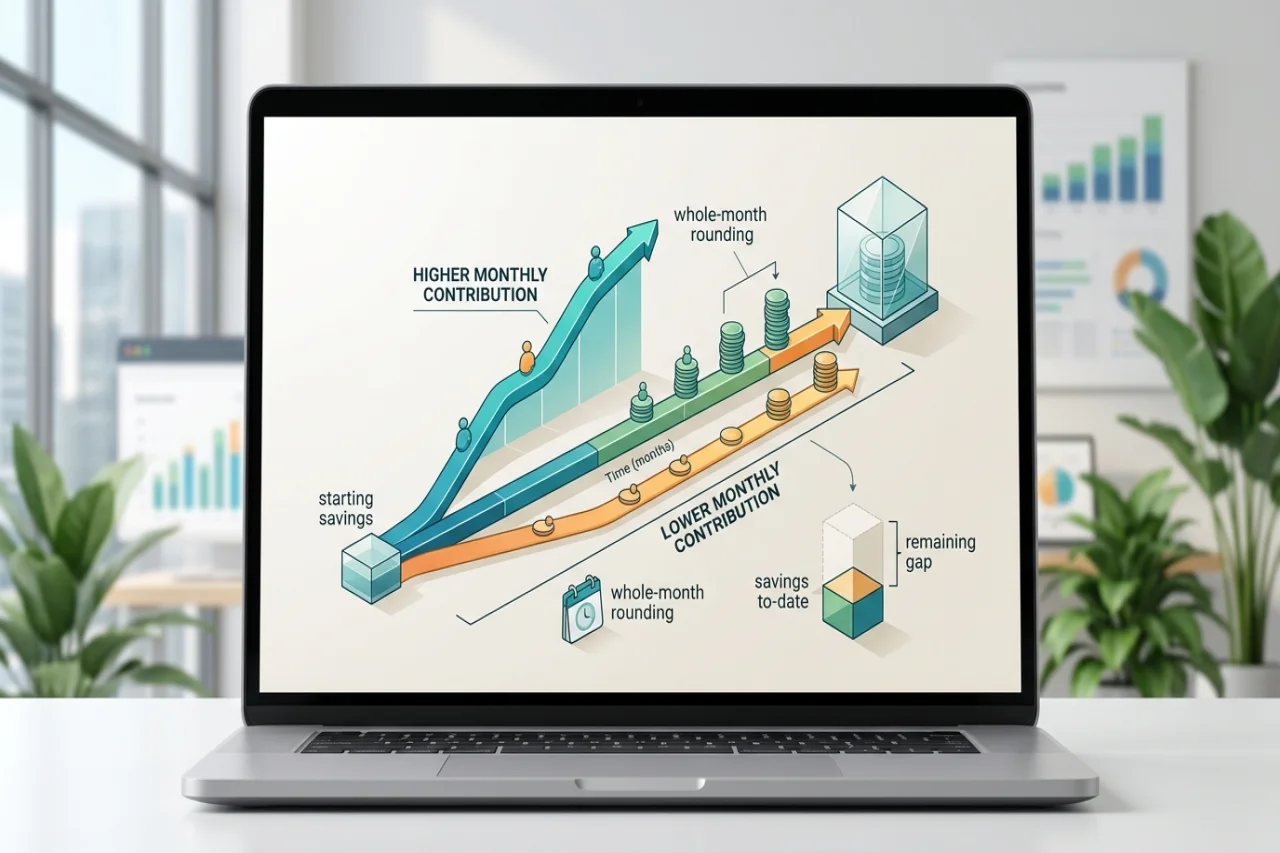
An emergency fund calculator helps make the pace of building a reserve visible. Its time result connects a chosen reserve and existing savings with the amount added each month, giving regular contributions a clear role.
For someone wondering what a monthly amount means over time, this can be useful. You can enter a contribution, read the timeline, and try another pace while the reserve itself stays the same.
This article focuses on that funding timeline, including the whole-month rounding that can otherwise make a result puzzling. The figures below are illustrative and assume steady contributions with no withdrawals.
1. Establish the Reserve Before Comparing the Pace
Use $2,500 in monthly essential expenses and a three-month coverage period. Multiplying those figures produces a $7,500 reserve scenario.
This is the amount the example is working toward. Keeping it unchanged during the exercise means any difference in the timeline comes from the savings inputs, making the effect of each contribution easier to see.
2. Subtract the Starting Savings
With $1,500 already saved, the remaining difference is $6,000. For example, the emergency fund calculator from Nevlin displays that gap alongside the selected reserve and the time implied by the monthly contribution.
This starting point is important. Funding a $7,500 reserve from zero is a different calculation than closing a $6,000 gap, even though both examples end up with the same final reserve amount.
3. Give a Monthly Amount a Visible Endpoint
At $250 a month, a $6,000 gap takes 24 months to close. A funding timeline connects that monthly contribution with a result you can picture.
This is useful when a recurring amount feels small beside a larger reserve. The timeline shows how repeated additions accumulate across a defined sequence of months.
4. Increase the Contribution and Compare
At $400 a month, the same gap takes 15 months. At $500, it takes 12 months. The reserve target and starting balance remain identical in all three examples.
These comparisons show the effect of the contribution without introducing a return assumption. You are looking at the relationship between money still to be added and the pace at which it is added.
5. Understand Why the Result Uses Whole Months
A contribution does not always divide evenly into the remaining difference. At $350 a month, $6,000 requires a little more than 17 contributions, so a calculator that rounds up to whole months shows 18 months.
After 17 contributions, $5,950 has been added and $50 remains. The next contribution reaches or passes the selected reserve. Thinking in completed monthly steps makes the rounded-up timeline easier to understand.
6. Distinguish Building Time From Coverage Time
In this example, three months describes the expense coverage being explored. Twelve, fifteen, or twenty-four months describes how long the selected contributions take to build it.
Keeping those meanings separate is important. Understanding the distinction lets you read a short reserve period alongside a longer funding timeline without mistaking one for the other.
7. Understand the No-Contribution Result
If a gap remains and the monthly contribution is set to zero, the reserve cannot be reached under that scenario. Entering a positive contribution gives the funding time a numerical result again.
That response makes the contribution’s role especially clear. The timeline follows the pace entered into the calculation, turning a question about recurring saving into a readable sequence.
Conclusion
Monthly contributions have a measurable effect on how long it takes to build an emergency fund. Calculating the remaining savings gap and comparing different contribution amounts helps illustrate that relationship. Understanding whole-month rounding and the distinction between coverage time and funding time also makes the results easier to interpret.
Comments
Comments are available to signed-in users and are moderated to keep the discussion useful and respectful. Spam, automated submissions, and low-value promotional comments are removed. Outbound links may be approved when they are relevant and genuinely helpful to readers, but they are displayed as plain text rather than clickable hyperlinks.
No comments have been published yet.
Please sign in to submit a comment.